

Blogs
Global Tool Presetter Market: by Type (Manual Tool Presetter, Semi-Automatic Tool Presetter, Automatic Tool Presetter), Application (Automotive, Aerospace, Metalworking, Electronics, Medical, Others), Distribution Channels (Direct, Distributors, Online, Retail, VARs, Others), Technology (Optical, Contact, Laser, Digital, Magnetic, Others), Organization Size (Small, Medium, Large) and By Global Historical & Forecast Period (2020-2035) Comprehensive Study 2025
Read More - https://bussinessinsights.com/research-report/global-tool-presetter
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-tool-presetter
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Market revenue for tool turrets is projected to grow steadily from 2020 to 2035, rising from $1,120 million in 2020 to an estimated $3,450 million by 2035. This trajectory highlights the sector's resilience and increased capital expenditure in automation solutions. The upward curve indicates robust demand, particularly in fast-growing manufacturing geographies and industries prioritizing digitalization, smart machining, and enhanced operational efficiency.
Read More - https://bussinessinsights.com/research-report/global-tool-turrets
The application landscape in 2025 sees automotive as the dominant sector for tool turret adoption because of high-volume and precision requirements, followed closely by aerospace and industrial machinery, driven by demand for quality, flexibility, and productivity in component manufacturing. Electronics and medical devices also represent significant market segments as micro-machining and precision finishing needs rise. Other sectors, including general engineering, contribute a smaller but steady share.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-tool-turrets
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
The global tool sharpener market revenue is set to surge from $2,100 million in 2025 to approximately $3,590 million by 2035, reflecting robust CAGR fueled by increased demand for automated sharpening solutions and recurring investment from emerging markets. Notably, the acceleration post-2027 is marked by rapid industrial adoption and new product launches in IoT-enabled and CNC-based technologies. The industry’s revenue trajectory signals sustained momentum, anchored by strong end-user adoption and continuous innovation.
Read More - https://bussinessinsights.com/research-report/global-tool-sharpener
The Industrial segment dominates the application landscape for tool sharpeners in 2025, accounting for the highest market share due to widespread usage in manufacturing and heavy-duty maintenance. Residential applications also capture a significant share, underscored by DIY culture and increased home improvement activities. Commercial and Educational Institute applications continue to grow, supported by expanding technical curriculum and training programs. Workshops and other specialized environments add further diversity to the market, underlining the universal need for sharp, efficient tools across sectors.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-tool-sharpener
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Wireless Communication Intelligent Module Market: Why 13.5% CAGR Reshapes Strategy
By PW Consulting, 2026-09-18
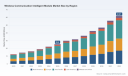
The Wireless Communication Intelligent Module Market: Navigating the Next Wave of Connectivity Growth
1. Market Landscape and Core Challenges
The wireless communication intelligent module market has entered a phase of sustained, high-velocity expansion. From 2020 through 2025, the sector compounded at a steady pace, crossing the twenty-five billion dollar threshold in the base year before accelerating into the forecast window. The growth trajectory points toward a double-digit compound annual growth rate through 2032, with revenue projections approaching sixty-two billion dollars by the end of the decade. This expansion reflects a structural shift rather than a cyclical upturn: intelligent modules are transitioning from peripheral connectivity components to core architectural elements in connected products across multiple verticals.
Geographic distribution of revenue reveals a market that is simultaneously mature in developed economies and rapidly scaling in emerging regions. Asia Pacific continues to generate the largest share of global revenue, driven by manufacturing density, consumer electronics demand, and accelerated industrial automation. North America and Europe maintain substantial, stable contributions, supported by automotive adoption, enterprise IoT deployments, and regulated connectivity standards. Latin America and the Middle East and Africa, while smaller in absolute terms, are expanding as infrastructure investment and digital transformation initiatives create new monetization pathways for wireless intelligent modules.
Technology segmentation further illustrates where value is concentrating. Cellular IoT dominates the technology mix, reflecting the broad applicability of licensed-band connectivity for mission-critical, mobility-heavy, and long-range deployments. Wi-Fi and Bluetooth remain essential for short-range, high-throughput, and cost-sensitive applications, particularly in consumer and enterprise environments. Low-power wide-area networks and satellite or ultra-wideband technologies occupy smaller but strategically important positions, enabling niche use cases in remote monitoring, asset tracking, and specialized positioning scenarios. On the application side, automotive and transportation represent the largest demand pool, followed by industrial IoT and consumer electronics. Smart city and utilities, along with healthcare, contribute meaningful but comparatively narrower revenue streams, each with distinct regulatory, reliability, and integration requirements.
Several structural challenges are shaping the market's inflection points. First, the competitive landscape is moderately concentrated, with a small group of established players accounting for the majority of global revenue. This concentration creates both pricing discipline and barriers for newcomers, while also intensifying pressure on incumbents to differentiate through performance, certification breadth, and application-specific optimization. Second, the industry is navigating a transition from volume-driven growth to value-driven design. Customers increasingly demand modules that integrate processing capability, edge intelligence, security features, and multi-standard interoperability rather than standalone connectivity silicon. This shift requires deeper engineering collaboration, longer qualification cycles, and more sophisticated lifecycle management. Third, supply chain and infrastructure dynamics are introducing new cost and timing variables. Rising material and deployment costs in adjacent infrastructure segments, including fiber and broadband construction, indirectly influence the economics of network-dependent modules by shaping rollout timelines and total cost of ownership for end customers.
These pressures do not diminish the market's growth potential; rather, they redefine where competitive advantage will be earned. Companies that align product roadmaps with regulatory momentum, application-specific reliability needs, and cost-aware design will be better positioned to capture share as the market matures. Understanding these inflection points is essential for any organization evaluating product strategy, procurement planning, or investment allocation in the wireless intelligent module space.
2. Key Drivers Shaping Market Trajectory
The market's expansion is not being pulled by a single force. Instead, several interlocking drivers are reinforcing each other, creating a compounding effect on demand, product evolution, and competitive behavior.
PW Consulting Information & Electronics Research Center
Technical innovation remains the most visible driver. Intelligent modules are increasingly defined by their ability to combine connectivity with on-device processing, improved power efficiency, and multi-protocol support. The emergence of reduced-capability cellular variants, such as RedCap, illustrates how the industry is expanding the addressable design space between full-featured 5G modules and low-bandwidth alternatives. These intermediate solutions enable manufacturers to deploy richer sensing, telemetry, and edge-computing functions without the cost and power profiles of flagship cellular platforms. Similarly, the integration of positioning, short-range radios, and cellular capabilities into unified intelligent module architectures is reducing integration complexity for OEMs and system integrators. The practical effect is faster time to market for connected products and a broader set of applications that can justify wireless connectivity in previously cost-sensitive or power-constrained contexts.
Regulatory and spectrum policy dynamics are another powerful catalyst. Authorities in key markets are altering the operating environment in ways that directly affect module demand and design choices. Recent rule changes aimed at easing technology transitions from legacy networks to IP-based infrastructure are reducing friction for operators and enterprises preparing for next-generation connectivity. Parallel efforts to expand the commercial spectrum pipeline create longer-term optimism around capacity, coverage, and new service models that can rely on wireless intelligent modules as enabling hardware. In specific regions, certification pathways and regulatory approvals are also becoming more structured, which helps module suppliers plan product lifecycles and gives end customers greater confidence in long-term support. At the same time, ongoing work to modernize spectrum sharing and allocate mid-band spectrum for advanced wireless services is shaping which standards and frequency bands module developers prioritize in their roadmaps.
Demand-side behavior is evolving as enterprises and consumers reassess what connected products must deliver. Purchasing decisions are increasingly influenced by total cost of ownership, reliability under real operating conditions, and the ability to support future feature upgrades without hardware replacement. In automotive and transportation, connectivity is no longer limited to infotainment or basic telemetry; it is becoming integral to fleet optimization, safety-related communications, and infrastructure interaction. In industrial IoT, the emphasis is shifting toward modules that can withstand harsh environments, maintain secure and deterministic communication, and support integration with analytics and automation workflows. Consumer electronics demand continues to reward compact, energy-efficient, and multi-standard solutions that can serve diverse usage scenarios without fragmenting bill-of-materials complexity. These preferences are pushing module suppliers to offer more application-tailored configurations, reference designs, and certification packages rather than generic connectivity components.
Supply chain and cost structure changes are adding both friction and opportunity. On one hand, input cost volatility and infrastructure deployment pressures in adjacent segments can complicate planning for network-dependent products. Rising material and labor costs in broadband and fiber deployment, for example, can influence rollout pace and indirectly affect the timing of demand for certain connectivity modules. On the other hand, these pressures are encouraging more disciplined design practices, including greater use of standardized form factors, platform-based development, and supplier partnerships that can share qualification risk. Companies that can stabilize lead times, manage component sourcing across regions, and provide clear migration paths between technology generations are gaining trust in segments where downtime or redesign cost is unacceptable.
Taken together, these drivers point to a market in which product excellence, regulatory awareness, and application-specific value creation matter as much as raw connectivity performance. Players that treat intelligent modules as part of a broader system solution, rather than as commoditized radio components, are likely to capture disproportionate value as demand broadens and matures.
3. Competitive Landscape and Leading Strategies
The competitive field is defined by a mix of global specialists, region-rooted scale players, and operator-affiliated or diversified technology firms. The leading companies share a common strategic imperative: build credible application coverage while differentiating on reliability, certification depth, platform integration, and lifecycle support.
Worldwide Wireless Communication Systems Market
Several established players have anchored their positions through broad cellular IoT portfolios and extensive certification footprints. These companies typically compete on the strength of their product breadth across 5G, LTE, low-power wide-area, and positioning technologies, as well as their ability to support automotive, industrial, and enterprise use cases with pre-validated designs. Their advantage often lies in offering customers a predictable migration path across generations, reducing qualification risk, and maintaining long-term availability for deployed systems. In practice, this means leading module suppliers are investing not only in silicon selection but also in firmware support, security frameworks, and regional compliance packages that make it easier for OEMs to scale across markets.
Other strong competitors have built differentiation through specialization. Some focus on high-reliability and security-oriented modules for industries where failure is not an option, emphasizing robust architectures, traceability, and certification for demanding environments. Others concentrate on cost-effective cellular and wireless solutions that address price-sensitive IoT, machine-to-machine, and smart applications, using lean product structures and efficient manufacturing to compete on value. A further group emphasizes embedded wireless modules for consumer electronics, industrial equipment, and automotive applications, leveraging integration expertise and compact form factors to serve design-constrained products. Operator-affiliated providers add yet another angle, drawing on network relationships and shipment scale in cellular IoT to support integrated connectivity solutions.
Recent product and market activity underscores how competition is evolving from catalog expansion to targeted, application-driven launches. In early 2026, multiple companies introduced or expanded 5G-capable modules and platform integrations designed for specific deployment contexts. New 5G NR sub-6 module series with platform-based architectures and railway-ready variants signaled growing attention to mobility, public-transport, and specialized communication standards. Parallel expansions in reduced-capability 5G portfolios reflected efforts to capture mid-tier use cases that need more capability than legacy low-power options but do not require full flagship performance. At the same time, flagship fixed-wireless and CPE-oriented solutions combining advanced 5G modules with high-performance processor platforms showed how module suppliers are increasingly positioning themselves within broader system-level solutions rather than selling connectivity in isolation.
Certification and market-access moves are equally important. Securing regional approvals for LTE Cat 1 bis and similar efficiency-focused modules illustrates how suppliers are building out addressable markets in geographies where cost, power, and coverage trade-offs favor leaner cellular options. Trade show showcases featuring next-generation IoT modules, AI-oriented platforms, and advanced 5G connectivity further highlight the industry's emphasis on embedding intelligence and future-proofing designs for evolving workloads. Collectively, these developments suggest a market where competitive advantage is being earned through a combination of technical readiness, regional compliance, and the ability to align module capabilities with application roadmaps.
Looking at the broader structure, the market appears to be moving toward selective consolidation in certain segments and continued fragmentation in others. In high-volume, standardized segments, scale, cost efficiency, and certification breadth will reward larger, well-resourced players. In specialized or vertically demanding applications, differentiation through reliability, integration, and domain expertise can sustain smaller or more focused competitors. New entrants face a real barrier in certification lead times, supply chain credibility, and the need to demonstrate long-term support, but targeted opportunities remain in emerging applications, region-specific requirements, and architectures that combine connectivity with edge intelligence in novel ways. The most resilient strategies are likely those that balance scale with specialization, allowing companies to serve broad demand while retaining the flexibility to win in higher-value niches.
4. Forward Outlook: Trends and Commercial Implications
Over the next three to five years, the market will likely be shaped by three interlocking trends. First, intelligent modules will increasingly be evaluated as integrated system enablers rather than radio components. Buyers will expect stronger combinations of connectivity, processing efficiency, security, and application-specific certification in a single design path. This trend favors suppliers that can offer cohesive platforms and reference architectures, and it raises the importance of firmware, lifecycle management, and migration planning.
Second, the spectrum and regulatory environment will continue to influence product priorities. Policy moves that ease network modernization and expand commercial spectrum access should support long-term demand for advanced wireless modules, while regional certification and sharing rules will keep shaping which standards and bands receive the most engineering focus. Companies that monitor regulatory timelines and align product roadmaps accordingly will be better positioned to capture emerging opportunities without costly redesigns.
Third, application demand will keep diversifying in ways that reward tailored solutions. Automotive and transportation, industrial IoT, and consumer electronics will remain core growth engines, but the most interesting margin opportunities may come from specialized deployments where reliability, power constraints, or integration complexity create room for higher-value module designs. Smart city, utilities, and healthcare will contribute incremental but strategically meaningful demand, especially where secure, dependable connectivity is non-negotiable.
These trends carry both opportunity and risk. On the opportunity side, broader intelligent module adoption opens the door to platform-based revenue models, longer customer relationships, and cross-selling into security, positioning, and edge-processing add-ons. On the risk side, input cost volatility, infrastructure deployment delays, certification bottlenecks, and the ongoing concentration of share among leading players can compress margins and raise entry barriers. Organizations that plan for these dynamics by diversifying supply, prioritizing application-relevant differentiation, and investing in regulatory readiness will be better prepared to convert market growth into durable commercial advantage.
5. Strategic Implications for Decision-Makers
For manufacturers and product leaders, the near-term priority is to align module selection with application realities rather than treating connectivity as a commodity input. The most effective strategies typically combine platform-based development, proactive certification planning, and clear migration paths across technology generations. Where possible, companies should evaluate suppliers not only on unit cost but also on qualification support, regional compliance coverage, power-performance balance, and the ability to support future feature upgrades without full hardware redesign.
For investors, the market offers a nuanced picture. Growth is robust, but value creation is increasingly concentrated in players that can combine scale with application-specific differentiation and disciplined lifecycle management. Due diligence should focus on product roadmaps, certification momentum, supply chain resilience, and exposure to both high-volume standards and specialized high-reliability segments. Companies that can demonstrate repeatable wins in demanding applications while maintaining cost competitiveness are likely to command more durable positioning than those competing primarily on price in commoditizing segments.
WiFi Modules Market
For procurement and procurement-led organizations, the strategic task is to balance cost, availability, and long-term support risk. Multi-source strategies, clear technical requirements for security and reliability, and early engagement with suppliers on regional certifications can reduce exposure to lead-time shocks and redesign costs. Establishing performance and compliance criteria before specification freezes helps ensure that module choices support both immediate deployment goals and future scalability.
Given the pace of product launches, regulatory activity, and application expansion, staying current with detailed segment data, competitive moves, and region-specific requirements is increasingly important. Deeper analysis of subsegments, technology transitions, and supplier-by-supplier positioning can help decision-makers refine product roadmaps, investment theses, and sourcing strategies with greater precision. For those seeking a fuller picture of market sizing by segment, competitive dynamics, and scenario-based guidance, the complete PW Consulting report provides the structured detail needed to support more granular planning decisions.
For detailed analysis of this topic, please visit the official page: Wireless Communication Intelligent Module Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fork Lifting Agvs Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-09-18
Fork Lifting AGVs Market
Overview
The Fork Lifting AGVs Market encompasses automated guided vehicles designed specifically for material handling tasks involving palletized or bulk goods. These systems are integral to modern warehouses, manufacturing plants, and distribution centers, enhancing operational efficiency and safety. By automating the transportation of heavy or bulky items, Fork Lifting AGVs support industries in reducing labor costs and increasing throughput.
The market's core functionalities include precise navigation, load management, and real-time integration with warehouse management systems. Fork Lifting AGVs Market plays a vital role in supporting Industry 4.0 initiatives, enabling smarter and more responsive supply chain operations. Their ability to adapt to complex environments makes them crucial for industries seeking scalable automation solutions.
Market Size and Growth
The current market value of the Fork Lifting AGVs Market is estimated at approximately USD 1.2 billion. Over the next decade, it is projected to reach around USD 4.8 billion, reflecting a compound annual growth rate (CAGR) of about 16%. Factors driving growth include increasing demand for automation in logistics, advancements in robotics technology, and the expansion of e-commerce fulfillment centers.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI2175
Key Drivers
• Rising adoption of warehouse automation solutions
• Technological advancements in navigation and load handling
• Growing need for operational safety and efficiency
• Expansion of e-commerce and retail logistics
• Industry focus on reducing labor costs and increasing scalability
Restraints
• High initial investment costs for automation systems
• Technical complexities in integration with existing infrastructure
• Limited operational flexibility in certain environments
• Regulatory hurdles related to safety standards and certifications
• Workforce displacement concerns impacting adoption
Segmentation
• By Type: Fixed, Mobile
• By Deployment: Indoor, Outdoor
• By Enterprise Size: Small and Medium Enterprises, Large Enterprises
• By End User: Manufacturing, Logistics & Warehousing, Retail, E-commerce
• By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
North America exhibits strong adoption driven by technological innovation and high labor costs, with a focus on safety and efficiency. Europe’s market growth is fueled by stringent regulations and industrial automation initiatives. In Asia-Pacific, rapid industrialization and rising e-commerce activity are boosting demand for Fork Lifting AGVs Market. Latin America shows emerging potential, primarily in manufacturing sectors, while the Middle East & Africa are gradually adopting automation to modernize logistics infrastructure.
Opportunities
• Expanding automation in emerging markets
• Integration of AI and machine learning for smarter navigation
• Development of versatile, multi-functional AGVs
• Adoption in food & beverage, pharmaceuticals, and heavy industries
• Growing interest in sustainable and energy-efficient solutions
Key Companies
Daifuku Co., Ltd., Toyota Industries Corporation, KUKA AG, Dematic, Seegrid Corporation, Swisslog Holding AG, JBT Corporation, Crown Equipment Corporation, KION Group, Mitsubishi Electric Corporation, FANUC Corporation, and Hyster-Yale Materials Handling.
Conclusion
The overall outlook for the Fork Lifting AGVs Market remains optimistic, with long-term growth driven by technological innovation and increasing industry automation. As industries seek more efficient and safer material handling solutions, the market’s strategic importance is set to expand. The market size and growth potential highlight the critical role of Fork Lifting AGVs Market in shaping future supply chain and manufacturing landscapes.
Related Reports
Polyurethane Foam Synthetic Sleeper Market , Size Share and Analysis | Report 2033
Bridge Sleepers Market , Size Share and Analysis | Report 2033
Transient Digital Recorder Market , Size Share and Analysis | Report 2033
Cyclone Boiler Market , Size Share and Analysis | Report 2033
Warp Beam Dyeing Machine Market , Size Share and Analysis | Report 2033
Hank Dyeing Machine Market , Size Share and Analysis | Report 2033
Cheese Dyeing Machine Market , Size Share and Analysis | Report 2033
Static Testing Machine Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher
Why Corporate LMS Adoption Is Leaving Legacy Systems Behind Through Cloud, SMEs and APAC Expansion in a $44.9B Market
By PW Consulting, 2026-09-18
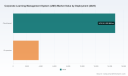
The Worldwide Corporate LMS Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The global corporate learning management system (LMS) market has transitioned from a mature support function into a strategic imperative for enterprise talent development. Valued at approximately $9.5 billion in 2020, the market expanded steadily through the mid-2020s, crossing the $16.7 billion threshold by 2024 and reaching an estimated $18.5 billion in 2025. Growth is projected to accelerate through the end of the decade, with the market expected to surpass $20.4 billion in 2026 and continue scaling toward $24.6 billion by 2027, $25.6 billion by 2028, $30.6 billion by 2029, $36.6 billion by 2030, $40.9 billion by 2031, and ultimately approaching $44.9 billion in 2032. This trajectory reflects a compound annual growth rate of roughly 13.51 percent across the 2026 to 2032 forecast horizon. The expansion signals a structural shift: learning platforms are no longer treated as administrative cost centers but as integral components of workforce transformation, compliance management, and competitive differentiation.
Despite the favorable growth trajectory, several structural challenges are reshaping vendor strategies and buyer expectations. First, data governance and privacy compliance have become non-negotiable constraints. Corporate LMS platforms must navigate complex regulatory environments, including GDPR Article 32 requirements for pseudonymization and encryption when processing employee training data, as well as CCPA mandates that grant California residents opt-out rights for personal data collected through LMS analytics. These obligations force vendors to embed privacy-by-design architectures and transparent data handling protocols, which elevate development costs and slow feature deployment cycles. Second, the cost structure surrounding cloud hosting and specialized labor is tightening margins for mid-tier providers. AWS EC2 pricing for LMS hosting typically ranges between $0.10 and $0.25 per hour for m5.large instances used in scalable deployments, while the average annual salary for LMS administrators in the United States hovers around $85,000. Together, these inputs pressure vendors to optimize infrastructure utilization and streamline platform administration without sacrificing user experience. Third, the market is experiencing a concentration of influence among a handful of scaled players, yet fragmentation remains across niche capabilities such as collaborative content creation, partner enablement, and industry-specific compliance workflows. This duality creates both a standardization pull and a customization demand, leaving enterprises to weigh integration simplicity against functional depth.
The current inflection point is defined by expectations for intelligent personalization, seamless HR ecosystem integration, and measurable skill outcomes rather than mere course completion. Vendors that treat the LMS as a static repository will struggle to retain enterprise buyers, while those that align learning delivery with real-time workforce analytics and regulatory readiness will capture disproportionate share.
PW Consulting
Key Growth Drivers
Technological Innovation and AI-Enabled Learning Experiences
Artificial intelligence has moved from experimental add-on to core architecture in modern corporate LMS platforms. Generative AI capabilities now power adaptive learning paths, content synthesis, and competency-based recommendations that adjust dynamically based on role, performance signals, and skill gaps. Vendors are embedding these capabilities directly into learning workflows rather than offering them as peripheral tools. For example, the introduction of generative AI features for personalized learning paths within enterprise learning suites has reduced manual curriculum design effort and accelerated time-to-competency for large workforces. In parallel, AI-assisted content creation tools have begun to compress course development cycles, enabling organizations to scale training production without linearly expanding L&D headcount. The strategic implication is clear: platforms that can convert raw learning signals into actionable development plans will command premium positioning, while generic content aggregators will face margin compression.
Policy and Regulatory Pressure as a Demand Catalyst
Regulatory compliance continues to be a durable demand driver, particularly in sectors with stringent training mandates and cross-border workforce operations. Privacy frameworks such as GDPR Article 32 and CCPA shape how LMS data is stored, processed, and shared, compelling vendors to invest in encryption, pseudonymization, and auditable access controls. Beyond privacy, the adoption of privacy information management standards like ISO/IEC 27701 provides a structured approach to handling employee learning data responsibly, which has become a differentiator in procurement evaluations. In practice, compliance is no longer a checkbox; it is a design requirement that influences platform architecture, deployment models, and customer trust. Enterprises operating across multiple jurisdictions increasingly favor LMS solutions that can centralize governance while supporting regional data handling rules, creating opportunities for vendors that can demonstrate both technical rigor and operational transparency.
Customer Support Training Software Market
Demand-Side Shifts in Corporate Learning Behavior
Enterprise learning behavior has fundamentally changed. Organizations are moving away from one-size-fits-all training catalogs toward skills-based development models that align learning with workforce planning, internal mobility, and performance outcomes. Collaborative learning models are gaining traction as companies recognize that employee-generated content and peer-led upskilling can scale faster than top-down course development. Adoption of collaborative LMS environments that enable employee-generated content and connect with collaboration tools has been evident in recent client engagements, including global upskilling programs for large consumer brands. Mobile-first design, gamification, and microlearning formats are also reshaping engagement patterns, especially for field teams and deskless workers who require on-demand access to training outside traditional classroom settings. These behavioral shifts reward platforms that prioritize usability, social interactivity, and just-in-time learning delivery over bulky administrative interfaces.
Cost Structure and Deployment Economics
The economics of LMS deployment are evolving as cloud maturity lowers entry barriers while specialized operational costs remain elevated. Cloud-based deployments have become the dominant preference for scalability and reduced infrastructure overhead, yet hosting costs and administrative labor still influence total cost of ownership. Scalable cloud hosting for LMS workloads, such as AWS EC2 m5.large instances, typically ranges from $0.10 to $0.25 per hour, and enterprise deployments must account for load balancing, storage growth, and integration maintenance. On the personnel side, specialized LMS administration roles carry meaningful salary expectations, with U.S. administrators averaging around $85,000 annually. The resulting pressure is pushing vendors to deliver stronger automation, simplified reporting, and embedded analytics that reduce manual oversight. Buyers, meanwhile, are weighing the trade-off between fully managed cloud environments and controlled on-premise deployments where data residency and customization requirements dominate. This economic reality is accelerating demand for platforms that combine elastic cloud scalability with operational efficiency features, including automated provisioning, self-service configuration, and intuitive admin dashboards.
Competitive Landscape and Leading Strategies
The corporate LMS market is shaped by a mix of established HCM suites, specialized learning platforms, and AI-focused entrants, each pursuing distinct strategic positions. Cornerstone OnDemand offers a comprehensive LMS built around AI-driven content recommendations, compliance tracking, and HR system integration, reinforcing its positioning as an end-to-end talent development platform. SAP provides enterprise-grade learning through its SuccessFactors ecosystem, emphasizing employee development, skills management, and virtual classroom capabilities, while also extending its footprint through acquired assets such as an LMS offering with pre-built course libraries, compliance training, and analytics tailored for sales and customer service teams. Workday integrates learning directly into its HCM suite, focusing on skills-based learning paths and personalized employee development, which aligns tightly with organizations seeking unified workforce data. Oracle delivers adaptive learning, content curation, and HCM Cloud integration through its learning cloud offering, appealing to enterprises that prioritize scale and ecosystem cohesion.
Beyond the suite players, specialized vendors are carving out differentiation through AI-native experiences, collaboration models, and targeted use cases. Docebo positions itself around AI-powered learning experiences, social learning features, and multi-tenant architecture designed for large corporations, and it has continued to expand its creative tooling by launching an AI content creation capability integrated into its LMS platform. TalentLMS emphasizes cloud-based corporate training with gamification, course e-commerce, and mobile-first design, and it has reinforced enterprise trust through security certifications such as SOC 2 Type II compliance. LearnUpon focuses on compliance, partner training, and sales enablement with multi-portal capabilities, while Absorb LMS targets enterprise training management through automation, e-commerce, and reporting features. 360Learning differentiates through collaborative learning that supports employee-generated content and integrations such as Microsoft Teams, and it has translated that positioning into enterprise wins for global upskilling initiatives. Together, these players illustrate a market where value is increasingly defined by how effectively a platform connects learning, work context, and measurable skill outcomes.
Strategic positioning is also being reshaped by partnerships and ecosystem integration. Integrations that connect learning platforms with collaboration and productivity tools, such as the partnership between Cornerstone OnDemand and Microsoft Viva Learning, highlight how LMS vendors are embedding learning into daily workflows rather than isolating it in a separate portal. This convergence suggests a market trend toward workflow-anchored learning, where platforms compete on seamless experience and context-aware content delivery more than on catalog size alone. At the same time, consolidation pressure remains: large suites continue to absorb niche capabilities, while independent vendors defend differentiation through speed, UX, and vertical specialization. New entrants are likely to challenge incumbents in AI-assisted content production, skills inference, and compliance automation, but scaling trust and enterprise integration depth will remain demanding barriers.
E-learning Corporate Compliance Training Market
Future Trends and Commercial Opportunities
Over the next three to five years, the corporate LMS market is likely to be defined by three interrelated trends. First, AI will become the primary mechanism for learning personalization and content operations. Expect broader adoption of adaptive learning paths, automated content generation, and skills inference that maps learning activities to workforce planning data. The commercial opportunity lies in platforms that can demonstrate measurable productivity gains from reduced course development time and improved skill alignment, especially for enterprises managing large, distributed workforces. Second, learning platforms will increasingly function as workflow-integrated skill orchestration layers rather than standalone training portals. As organizations consolidate HR, performance, and learning data, LMS solutions that integrate directly with collaboration tools and HCM ecosystems will gain preference, creating opportunities for vendors that can deliver context-aware learning within everyday work environments. Third, compliance and privacy governance will become deeper differentiators. Enterprises operating under multi-jurisdiction data rules will favor platforms that can prove strong encryption, pseudonymization, and auditable data handling practices, while also supporting privacy management standards relevant to learning data.
These trends create clear commercial openings for vendors and buyers alike, but uncertainty remains. Rapid AI adoption may outpace internal governance capabilities, leading to content quality concerns and skill measurement challenges if models are not carefully supervised. Cost volatility in cloud infrastructure and specialized talent can strain deployment economics, particularly for organizations pursuing ambitious scale without proportional operational maturity. Finally, as suites consolidate capabilities, independent vendors will need to defend defensible niches or deliver materially superior user outcomes to maintain pricing power.
Strategic Recommendations for Decision-Makers
For enterprise buyers evaluating LMS investments, prioritize platforms that connect learning delivery to skills data, workflow integration, and compliance readiness rather than catalog breadth alone. Assess how well a solution integrates with existing HCM and collaboration tools, how transparently it handles employee data under applicable privacy obligations, and whether its administration model reduces ongoing operational burden. For investors and strategic partners, focus on vendors with credible AI-enabled content and personalization capabilities, strong ecosystem integration roadmaps, and demonstrable traction in enterprise-scale deployments. Vertical specialization, security certifications, and measurable customer outcomes will be key indicators of durable differentiation. For platform vendors and service providers, the opportunity lies in reducing friction across content creation, deployment, and measurement while strengthening governance features that satisfy cross-border privacy demands. Aligning product roadmaps with workflow-anchored learning and cost-efficient cloud operations will be essential to competing as the market scales. For decision-makers seeking a deeper view of segmentation dynamics, regional deployment patterns, and customized scenario planning, the full research report provides extended data and tailored recommendations to support precise commercial strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Corporate Learning Management System (LMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Water Soluble Pastes Market: Asia Pacific’s 6% CAGR Trajectory Explained
By PW Consulting, 2026-09-18
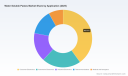
Global Water Soluble Pastes Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The water soluble pastes market, particularly within the electronics assembly sector, is navigating a period of structured expansion underpinned by steady revenue growth. Measured in USD millions, the market has demonstrated consistent upward momentum over the historical period from 2020 through 2025, with cumulative revenue climbing from approximately 385 million to over 512 million. The forward trajectory through the 2026 to 2032 forecast window projects continued scale, with annual revenue expected to surpass 770 million by the end of the period. This progression translates to a compound annual growth rate hovering around 6 percent, signaling a mature yet resilient demand environment rather than a speculative surge.
Beneath the headline figures lies a market shaped by clear structural preferences. Lead-free water soluble formulations now dominate total revenue, reflecting entrenched regulatory and manufacturing realities that have made traditional leaded variants a minority share. Application demand is heavily anchored in consumer electronics and automotive electronics, which together account for the largest revenue concentration, while industrial electronics, telecommunications, and medical or aerospace applications form substantial secondary pillars. Geographically, the Asia Pacific region commands the largest revenue contribution, followed by North America and Europe, with Latin America and the Middle East and Africa representing smaller but steadily participating slices of global demand.
Despite this orderly growth path, the industry faces several inflection points that decision makers cannot overlook. First, formulation performance is being tested by increasingly dense and miniaturized assembly requirements. As component pitch shrinks and mixed-technology boards become standard, water soluble pastes must balance high activity and reliable wetting with cleanability and residue control. Second, environmental and process compliance continues to tighten across multiple manufacturing jurisdictions. Halogen-free and low-residue expectations are no longer niche preferences; they are becoming baseline requirements that influence material selection, validation cycles, and qualification costs. Third, the supply chain for specialty chemistries and high-purity alloy materials remains sensitive to price volatility and regional capacity shifts, creating margin pressure for manufacturers that rely on single-source inputs or inflexible procurement models.
These challenges are not solely constraints; they are also markers of where innovation and commercial positioning will be rewarded. Companies that can deliver repeatable fine-pitch printability, stable performance in lead-free processes, and straightforward cleaning with deionized water are better placed to capture demand from advanced assembly environments. At the same time, the market's moderate concentration, with the top three players holding a meaningful share and the top five approaching just over half of total revenue, suggests that scale advantages exist but are not insurmountable. That leaves room for differentiated performers to gain ground through formulation specificity, application engineering support, and regional service depth.
For executives and investors, the immediate implication is that growth in this space will be earned through reliability, compliance readiness, and process compatibility rather than through broad commodity positioning. The next phase of expansion will likely favor participants who can align product portfolios with the technical demands of lead-free, increasingly miniaturized electronics manufacturing while managing input-cost exposure.
Key Demand and Supply Drivers
Several interlocking drivers are shaping the pace and direction of the water soluble pastes market. The most visible is the ongoing transition to lead-free electronics assembly. Global restrictions on lead-containing materials have made lead-free formulations the default choice across mainstream board-level and semiconductor packaging applications. This shift is not simply a compliance exercise; it has reshaped formulation chemistry, process windows, and qualification expectations. Manufacturers designing for lead-free processes need pastes that maintain strong wetting, resist graping, and produce residues that can be removed cleanly without compromising adjacent components or underfill interfaces. As a result, advanced water soluble systems have become integral to meeting both performance and regulatory expectations in modern assembly lines.
Water Soluble Fertilizers Market
Closely linked to this transition is the growing adoption of halogen-free and low-residue formulations. Environmental regulations across multiple countries are pushing electronics manufacturers toward materials that reduce hazardous substance exposure while maintaining process robustness. Halogen-free water soluble pastes are increasingly selected for applications where long-term reliability, humidity resistance, and worker safety considerations intersect. This trend is particularly relevant for high-volume consumer electronics and automotive electronics, where qualification cycles are rigorous and material consistency directly affects yield. The momentum behind halogen-free options signals a broader industry preference for materials that simplify downstream compliance and reduce the risk of failed audits or customer-specific requirements.
A second major driver is the technical demand created by finer-pitch assembly and advanced packaging formats. Surface mount technology continues to handle smaller geometries, and system-in-package designs, flip-chip interconnections, and microdispensing applications are becoming more common in high-performance devices. These applications place stringent requirements on paste printability, slump control, voiding behavior, and residue profile. Water soluble pastes engineered for ultrafine-pitch printing and controlled deposition are therefore gaining relevance not only in traditional PCB assembly but also in semiconductor packaging processes that require precise material placement and reliable joint formation. In this environment, formulations that combine high activity with manageable residue characteristics provide a practical advantage because they reduce cleaning complexity while supporting tighter process controls.
The third driver lies in end-market demand patterns and manufacturing economics. Consumer electronics continues to be a large revenue contributor because of its scale and cadence of product refreshes, which sustain steady material consumption. Automotive electronics is another pivotal demand source, driven by increasing electronic content in vehicles and the need for dependable interconnections under demanding operating conditions. Industrial electronics, telecommunications infrastructure, and medical or aerospace applications add further layers of demand, each with distinct tolerance for cost, qualification depth, and performance margins. What unites these segments is a growing preference for materials that can support high-throughput manufacturing without introducing cleaning bottlenecks or reliability risks. Water soluble systems that can be removed efficiently with deionized water, even after extended processing intervals, address a practical production concern that influences line efficiency and total cost of ownership.
On the supply side, cost structures and material availability remain important variables. Specialty fluxes, alloy powders, and purity-controlled inputs can be exposed to pricing fluctuations and regional supply constraints. At the same time, manufacturers are under pressure to maintain competitive pricing while funding formulation improvements and application support. This creates a strategic tension: participants must invest in performance-enhancing chemistry and technical service, yet they must also manage input costs and avoid sacrificing consistency. Companies that develop robust supplier relationships, diversified sourcing strategies, and formulation platforms capable of serving multiple assembly needs are better positioned to absorb these pressures.
Recent product activity reflects these dynamics. Updates to solder paste catalogs have reinforced the availability of water soluble types for lead-free, RoHS-compliant circuit board assembly, indicating that suppliers continue to align portfolios with mainstream regulatory and performance expectations. Such moves are less about dramatic market disruption and more about sustaining relevance in a market where compliance, cleaning efficiency, and print reliability are baseline expectations. In practice, the companies that stand out are those that connect product updates to specific assembly challenges, whether that means lower voiding in lead-free processes, improved print definition, or residues that remain easy to remove after storage or extended handle time.
Competitive Landscape and Leading Strategies
The competitive field in water soluble pastes is populated by a mix of established materials suppliers and specialized formulation providers, each pursuing distinct routes to differentiation. Indium Corporation offers a broad range of water-soluble solder pastes, including versatile PCB assembly formulations and ultrafine-pitch printing options for SiP designs, alongside water-wash formulations used in semiconductor packaging and microdispensing applications. Its positioning suggests a strategy centered on breadth of application coverage and performance balance, particularly where low voiding, good wetting, and controlled printing are equally important.
Electrode Paste Market
MacDermid Alpha, encompassing ALPHA and Kester brands, contributes water-soluble solder pastes aimed at semiconductor and board-level assembly. Its focus on fine-pitch printing, low voiding, and easy cleaning in lead-free processes aligns with the core requirements of high-volume electronics manufacturing. By maintaining multiple brand touchpoints and application-specific options, the company can address both mainstream assembly and more demanding packaging environments. AIM Solder pursues a similar practical orientation, offering water-soluble pastes that emphasize strong wetting, low slumping, and residues that remain cleanable with deionized water even after extended time. That kind of cleaning resilience is especially valuable for operations where boards may not be immediately processed after printing.
In the semiconductor-oriented segment, Senju Metal Industry manufactures water-soluble fluxes and pastes for wafer bumping, ball attach, and PCB reflow applications. Its presence underscores the importance of materials that can support both board-level and component-level interconnection processes. Heraeus Electronics adds a European perspective with water-soluble pastes designed for halogen-free, fine-pitch printing in SiP, flip-chip, and ultrafine applications, where low voiding and good cleanability are central value propositions. Henkel, through its Loctite brand, provides water-washable and soluble pastes with halogen-free, temperature-stable formulations that support humidity resistance and high-activity performance. This breadth allows the company to serve customers who need materials that perform consistently across varied environmental and process conditions.
Smaller or more specialized players also play meaningful roles. Inventec Performance Chemicals delivers water-soluble solder pastes that emphasize exceptional wetting, reliable joints, and easy deionized water cleaning for lead-free SMT printing and soldering. FCT Solder focuses on water-soluble lead-free options with strong printability, wetting, and low graping characteristics, alongside warm-water clean residues that simplify process handling. Qualitek International offers Delta series water-soluble pastes for both Sn/Pb and lead-free SMT assemblies, with formulations oriented toward print definition, high tack, and easy cleaning. SHENMAO Technology rounds out the field with a full line of water-soluble solders and fluxes for SMT and IC packaging applications, reinforcing the importance of regional manufacturing depth and broad product availability.
What separates leading players is not merely product presence but the ability to translate formulation capabilities into application-specific advantages. The most effective strategies tend to combine several elements: formulation stability for lead-free and halogen-free requirements, print performance suited to fine-pitch and mixed-technology boards, residue behavior that simplifies cleaning, and technical support that helps customers qualify materials faster. Suppliers that can demonstrate consistent results across these dimensions often gain preference in environments where downtime, rework, and validation delays carry significant cost.
The market structure suggests continued differentiation rather than uniform consolidation. While the leading group holds a meaningful share, the field remains wide enough for specialized entrants and regional players to compete on performance, service, or price. Over time, the likely evolution will be a layered landscape: large multi-brand suppliers will continue to cover broad application portfolios, while focused providers may gain traction in niche areas such as ultrafine-pitch printing, semiconductor packaging, or regional lead-free compliance needs. New entrants will need to bring something concrete to the table, whether that is a formulation advantage, a cleaner process profile, or a stronger application engineering capability. Price competition will persist, but the more durable competitive advantage will come from reducing total process friction, not simply lowering unit cost.
Future Trends and Commercial Implications
Over the next three to five years, the water soluble pastes market is likely to be shaped by three reinforcing trends. The first is deeper entrenchment of lead-free and halogen-free formulations as default materials rather than special cases. As qualification standards mature and customer expectations stabilize around environmentally compliant materials, the competitive edge will shift from proving compliance to demonstrating process reliability within compliant formulations. Suppliers that can provide repeatable performance across lead-free chemistries, with predictable wetting and cleanability, will be better positioned to secure long-term supply agreements in high-volume segments.
The second trend is the expanding relevance of advanced packaging and fine-pitch assembly requirements. As devices become more integrated and board real estate more constrained, material behavior at small geometries will matter more than ever. Water soluble pastes that support ultrafine-pitch printing, controlled deposition, and low voiding will see continued demand from both PCB assembly and semiconductor packaging applications. This trend also creates an opportunity for suppliers to bundle material offerings with process guidance, printing recommendations, and cleaning protocols, turning product sales into broader process support engagements.
PW Consulting
The third trend is the growing emphasis on total cost of ownership rather than sticker price alone. Manufacturers are increasingly attentive to cleaning time, residue-related reliability risk, storage stability, and rework exposure. Water soluble systems that can be removed efficiently with deionized water, even after delays, and that maintain consistent performance through typical production intervals will be favored in cost-sensitive but quality-driven environments. This creates commercial opportunity for suppliers that can quantify process benefits in operational terms, such as reduced cleaning burden, fewer defect-driven interruptions, or smoother qualification cycles.
At the same time, uncertainty remains. Regulatory expectations can continue to tighten, and regional differences in material acceptance may complicate global product strategies. Input-cost volatility and supply continuity for specialty materials could pressure margins, especially for participants with limited sourcing flexibility. In addition, demand growth will not be uniform across applications or regions, meaning that portfolio alignment and regional execution will matter as much as overall market expansion. Companies that treat these uncertainties as planning variables, rather than external noise, will be better prepared to adjust formulations, service models, and commercial terms as conditions evolve.
Strategic Guidance for Decision Makers
For manufacturers, the priority is to align material selection with the practical demands of lead-free, increasingly miniaturized assembly. That means evaluating water soluble pastes not only on baseline performance but also on print definition, voiding behavior, residue cleanability, and stability over typical storage and handling intervals. Building qualification pipelines around formulations that support fine-pitch printing and straightforward deionized water cleaning can reduce process friction and shorten the path to reliable volume production. Supplier partnerships should be judged on application support and consistency as much as on unit pricing.
For investors, the most compelling exposure lies in participants that combine compliance-ready chemistry with differentiated performance in high-growth applications such as consumer electronics, automotive electronics, and advanced packaging. Business models that rely on broad commodity positioning without clear technical differentiation face greater risk in a market where cleaning efficiency, reliability, and regulatory alignment increasingly determine purchasing decisions. Monitoring portfolio updates, formulation focus, and application-specific claims can provide early signals about which players are likely to defend or expand their positions.
For procurement and supply chain leaders, the strategic task is to balance cost control with resilience. Diversifying approved materials where possible, securing visibility into lead-free and halogen-free compliance status, and evaluating total process cost rather than paste price alone can improve operational stability. Where feasible, favor suppliers that can demonstrate consistent cleaning performance and provide documentation or technical support that simplifies downstream validation. In a market where the top five players account for just over half of revenue, there is room to structure sourcing strategies that preserve optionality while maintaining performance standards.
Detailed regional splits, application-level revenue breakdowns, and company-specific positioning data can sharpen these decisions further. The broader market signals are clear, but the most useful next step is to connect them to the specific product categories, end-use segments, and regional conditions that shape individual procurement and investment choices.
For detailed analysis of this topic, please visit the official page: Worldwide Water Soluble Pastes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Shaving Foam Market: What 4.12% CAGR and $771.88M Reveal by 2032
By PW Consulting, 2026-09-18
Navigating the Worldwide Shaving Foam Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The global shaving foam market sits at an inflection point. Valued at approximately $581.85 million in 2025, the sector has navigated a period of fluctuating demand since 2020, when baseline revenue hovered around $485.2 million. A contraction in 2021 to $472.08 million gave way to a resilient recovery, with annual revenue climbing to $522.76 million in 2022, $533.53 million in 2023, and $580.62 million in 2024. Projections indicate a steady expansion trajectory through 2032, with revenue expected to reach $771.88 million, supported by a compound annual growth rate of 4.12 percent across the 2026-2032 forecast window. This growth profile underscores a market that is neither collapsing under digital grooming alternatives nor exploding into hypergrowth, but rather maturing through incremental value creation, formulation upgrades, and channel realignment.
Despite this baseline stability, the industry faces structural headwinds that will define competitive outcomes over the next half-decade. First, regulatory scrutiny over chemical composition and aerosol propellants is intensifying. Notices issued in 2024 under California Proposition 65 highlighted the presence of listed substances such as Nitrous Oxide and Diethanolamine in select shaving foam products, prompting manufacturers to reassess formulation roadmaps and transparency standards. Simultaneously, the FDA and international cosmetic regulators continue to refine ingredient safety expectations, emphasizing good manufacturing practices and imposing tighter restrictions on certain preservatives and propellants. For brands built around aerosol convenience, compliance costs and reformulation timelines represent a non-trivial operational drag.
Second, the rise of sensitive-skin and moisturizing formulations is reshaping demand hierarchies. Consumers are increasingly treating shaving foam not as a disposable lubricant but as a skincare-adjacent product, prioritizing reduced irritation, hydration, and post-shave comfort. This shift pressures legacy mass-market lines to justify their positioning against premium, dermatologically informed alternatives, while also complicating inventory and production planning for suppliers that have historically optimized for high-volume, low-differentiation outputs. Third, distribution channel dynamics are fragmenting value capture. Hypermarkets and supermarkets continue to drive substantial volume, yet online retail and pharmacy channels are gaining share as consumers seek specialized formulations, subscription convenience, and expert recommendations. Brands that rely heavily on legacy retail shelf placement must contend with margin compression and channel conflict as digital and specialty routes mature.
Key Value Drivers
Three interlocking forces are reshaping the competitive and commercial landscape for shaving foam. The first is formulation technology and sustainability integration. Manufacturers are accelerating the transition toward plant-based surfactants and eco-friendly propellants, with adoption of recyclable packaging gaining momentum between 2023 and 2025. This is not merely a compliance exercise; it is a repositioning strategy. Brands that can deliver comparable glide, lather stability, and skin comfort while reducing irritants and environmental footprint are capturing credibility with increasingly informed buyers. The trend also intersects with cost optimization, as ingredient substitution programs are being paired with packaging redesign to control total landed cost while meeting retailer sustainability mandates.
The second driver is demand-side evolution in personal grooming behavior. Rising awareness of skin protection and grooming as part of broader self-care routines is expanding the addressable use case for shaving foam. Sensitive skin and moisturizing variants are leading this incremental demand, reflecting a consumer base that expects performance without compromise. For established players, this creates an opportunity to expand within existing customer bases by layering skincare benefits onto core shaving products. For newer entrants, it opens a pathway to differentiation through ingredient storytelling, dermatological endorsements, and targeted product architecture. The practical implication is that product portfolios must increasingly be evaluated through a dual lens: functional shaving performance and skin condition outcomes.
The third driver is regulatory and compliance pressure, which operates as both constraint and catalyst. Ingredient safety standards, aerosol propellant restrictions, and good manufacturing expectations are raising the bar for market entry and product iteration. While this burdens smaller players with formulation and documentation requirements, it also creates a moat for companies that have invested in regulatory competence, supply chain traceability, and quality systems. The regulatory environment is not uniform across regions, meaning that global brands must manage a patchwork of requirements while preserving brand cohesion. Companies that internalize compliance as a product development capability rather than a reactive function are better positioned to launch faster and with fewer regional friction points.
The fourth driver is strategic consolidation and channel leverage. Recent moves illustrate how incumbents are using acquisition, collaboration, and portfolio rationalization to sharpen positioning. Unilever's completion of its acquisition of Dr Squatch in mid-2025 expanded its premium men's grooming footprint and created potential synergies with shaving foam offerings. Procter & Gamble outlined a productivity-focused strategy in mid-2025 that emphasized grooming innovation alongside cost discipline, signaling a dual emphasis on value creation and operating efficiency. At the same time, Gillette's collaboration with the National Basketball Youth Mentorship Program in early 2024 highlighted how grooming education and product awareness can be embedded within community-focused initiatives. These developments reflect a broader pattern: incumbents are using scale, brand architecture, and purpose-led engagement to defend share and extend reach, while smaller brands pursue niche credibility and direct engagement.
Competitive Landscape and Leading Strategies
The market is characterized by a concentrated core and a long tail of specialized and regional players. The three-firm concentration ratio stands at 42.5 percent, while the five-firm concentration ratio reaches 58.8 percent, indicating that a relatively small group of multinationals controls a majority of revenue, but that considerable fragmentation remains outside the top tier. This structure shapes how strategy is executed: leading firms compete on portfolio breadth, formulation credibility, distribution leverage, and brand equity, while challengers compete on specificity, price-value positioning, and channel agility.
The Procter & Gamble Company occupies a central position through its Gillette shaving foam and gel portfolio, anchored in performance, skin protection, and innovation across aerosol and non-aerosol formats. Its scale enables sustained investment in product architecture for both sensitive and regular skin, while its grooming segment integration supports cross-product synergy and retail negotiation power. P&G's productivity-focused strategy underscores a discipline to fund innovation without sacrificing margin goals, a balance that is increasingly important as input costs and compliance demands rise.
Edgewell Personal Care competes through Schick, Wilkinson Sword, and Bulldog, emphasizing wet-shave comfort, sensitive skin formulations, and sustainable options. Its brand architecture spans mass and value segments, with Bulldog providing a differentiated personality lane that appeals to consumers seeking a less traditional grooming narrative. By balancing comfort claims with sustainability cues, Edgewell addresses both functional and emotional purchase drivers, an approach that helps defend share in a category where product perception often hinges on feel and after-effects.
Beiersdorf AG leverages NIVEA Men to connect shaving foam with moisturizing, cooling, and sensitive skin variants, drawing on dermatological expertise for global distribution. This positioning allows the brand to present shaving foam as part of a broader skin care logic, which is especially effective in markets where consumers respond to clinical credibility and familiar brand trust. Unilever PLC, through Axe and Dove Men+Care, targets younger consumers with grooming and skin care benefits in aerosol formats, using brand personality and lifestyle association to sustain relevance. L'Oréal Groupe contributes a skincare technology angle, integrating hydration and protection into men's grooming lines and benefiting from its broader cosmetics innovation pipeline.
Along the value and specialty edges, Colgate-Palmolive Company supplies shaving foams within its personal care portfolio, focusing on everyday grooming needs and channel reach. Perio, Inc. (Barbasol) positions Barbasol and Pure Silk as affordable, high-value aerosol products manufactured in the USA, a strategy that resonates with price-conscious consumers and retail buyers seeking reliable supply. Harry's Inc. combines modern formulations with a direct-to-consumer model, emphasizing quality and sustainability as differentiation levers. The Cremo Company has gained traction through premium shaving creams with natural ingredients, thick lather, and skin conditioning, illustrating how product sensory attributes can drive share in a category where perceived quality often translates into repeat usage. DORCO Co., Ltd. and VI-John Group extend the landscape into value-oriented grooming for domestic and export markets, with DORCO pairing foams with razors and VI-John targeting emerging markets through varied scent and skin-type formulations. Bombay Shaving Company and Kao Corporation round out the field with premium-plus and region-specific approaches, the former emphasizing natural positioning for Indian and select international markets, the latter aligning with local preferences for mild and effective formulations.
PW Consulting
The landscape is evolving along three trajectories. Consolidation is likely to continue as larger players acquire niche brands or grooming platforms to fill portfolio gaps and accelerate premiumization, as seen in recent acquisition activity. Differentiation is intensifying around skin sensitivity, sustainability, and sensory performance, which raises the stakes for formulation and claims substantiation. At the same time, new entrants and regional specialists are carving out defensible positions through direct engagement, localized product design, and channel strategies that bypass traditional shelf dependence. The net effect is a market where scale provides cost and distribution advantages, but where relevance increasingly depends on product credibility and consumer trust.
Foaming Creamer Market
Future Trajectory: 2026 to 2032 Outlook
Looking ahead, the market is poised to expand steadily toward the high-$700 million range by 2032, with the 4.12 percent CAGR reflecting incremental rather than disruptive growth. Several trends will shape value creation during this period. First, sensitive-skin and moisturizing formulations will continue to outpace generic mass variants in growth intensity, not because consumers are abandoning basic options, but because premiumization within core usage is becoming the primary growth engine. Brands that can deliver demonstrable comfort, reduced irritation, and post-shave skin benefits will capture disproportionate share of wallet.
Second, sustainability and compliance will converge as a product requirement rather than a marketing add-on. The shift toward plant-based surfactants, recyclable packaging, and reduced-irritant ingredient profiles is becoming embedded in retailer expectations and consumer preferences alike. Companies that integrate these attributes into core production processes will face fewer launch delays and fewer regional friction points, while laggards risk reputational and operational exposure. Third, channel reconfiguration will persist, with online retail and pharmacy channels gaining structural share as consumers seek specialized products and expert guidance. This will pressure traditional mass retail dependence and reward brands with strong digital commerce capabilities, clear product differentiation, and effective subscription or replenishment models.
The commercial opportunities are evident. Portfolio expansion into hybrid shaving-skincare products, targeted sensitive-skin lines, and refill or recycling programs can unlock incremental revenue while aligning with evolving consumer expectations. Strategic partnerships and selective acquisitions can accelerate premium positioning and geographic reach. For suppliers, formulation expertise and sustainable packaging capabilities are becoming differentiators in their own right, creating upstream value beyond brand marketing. The principal uncertainties are regulatory variability across markets, input cost volatility for surfactants and propellants, and the risk that premiumization stalls if economic pressures compress discretionary spending. Brands that manage these risks through flexible formulation pipelines, diversified sourcing, and disciplined pricing architecture will be better equipped to convert trend momentum into durable share gains.
Beard Shave Formula Market
Actionable Guidance for Decision-Makers
For manufacturers, the priority is to align product architecture with the sensitive-skin and sustainability trajectory while protecting operational discipline. That means investing in formulation pipelines that can satisfy both performance expectations and tightening regulatory standards, and designing packaging and propellant strategies that reduce long-term compliance and cost exposure. Portfolio reviews should prioritize variants with credible skin-care benefits and recyclable or reduced-impact packaging, and development cycles should anticipate regional ingredient rules rather than react to them.
For investors, the focus should be on differentiation durability and channel resilience. Companies with strong brand equity in premium or sensitive-skin segments, robust formulation capabilities, and the ability to operate across both physical retail and online channels are better positioned to defend margins in a market where concentration remains high but fragmentation persists at the edges. Acquisition and partnership activity will likely continue to reshape portfolios, so evaluating target brands for formulation credibility, direct-to-consumer traction, and sustainability readiness can reveal value that is not immediately visible in headline revenue figures.
For procurement and retail stakeholders, the strategic task is to ensure assortment clarity and supply reliability. As product differentiation increases, shelf and digital navigation become more complex, making it important to select partners with consistent quality, transparent ingredient positioning, and packaging that supports sustainability commitments. Suppliers that can demonstrate stable sourcing for surfactants and propellants, along with credible claims substantiation, will reduce assortment risk and improve consumer trust. In a market where growth is steady but competitive intensity is rising, timely access to detailed segmentation data, regional dynamics, and company-level strategy updates is essential for shaping investment, product, and channel decisions with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Shaving Foam Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Medical Device Package Validation Market: Why 7.2% CAGR Reshapes Compliance
By PW Consulting, 2026-09-18
Navigating the Medical Device Package Validation Market: Strategic Shifts and Commercial Opportunities (2026-2032)
Market Overview and Core Pressures
The medical device package validation market has demonstrated consistent expansion over the past five years, growing from a valuation of approximately USD 550 million in 2020 to USD 780 million in 2025. Projections indicate that this trajectory will continue through the forecast window, with the market expected to reach nearly USD 1.27 billion by 2032, representing a compound annual growth rate of 7.2 percent. This sustained growth reflects the critical role that packaging validation plays in the broader medical device lifecycle, where regulatory compliance, patient safety, and product integrity intersect. North America continues to command the largest share of global revenue, followed by Europe and Asia Pacific, while emerging regions such as Latin America and the Rest of World represent smaller but steadily growing demand pools. By test type, seal strength testing and integrity testing account for the majority of commercial activity, with shelf life and stability testing and microbial challenge testing forming the remainder. Packaging formats such as pouches and trays drive the largest portions of testing volume, with blister packs representing a secondary but meaningful segment.
Despite this positive outlook, the industry stands at a pivotal juncture shaped by several structural challenges. First, raw material cost dynamics have introduced new complexity into packaging production and validation planning. Medical-grade polyethylene and polypropylene prices have risen by 15 to 20 percent since 2024, driven by supply dislocations that ripple through manufacturing cost structures and validation sequencing. Second, the regulatory environment is evolving in ways that require validation providers and device manufacturers to reassess their compliance frameworks. While ISO 11607-1 and -2 remain the principal standards governing validation of terminally sterilized medical device packaging systems, state-level extended producer responsibility laws in jurisdictions such as Oregon and California are creating new questions around eco-modulated fees, recyclability expectations, and the scope of exemptions for sterile-labeled Class II and III devices. Third, demand is shifting toward more complex packaging configurations and distribution simulations that test products under increasingly realistic temperature, humidity, and mechanical stress conditions. These pressures are not isolated; they interact to create a landscape where validation is no longer a compliance checkbox but a dynamic strategic function.
For executives and investors, the implication is clear. The market's growth is real, but it is being reshaped by cost volatility, regulatory ambiguity, and higher performance expectations. Organizations that treat validation as a back-end activity risk bottlenecks, while those that integrate validation strategy earlier in design and supply chain planning are better positioned to manage cost, compliance, and speed to market.
Key Drivers of Market Change
Technology Innovation and Testing Sophistication
Advancements in testing methodology are redefining what validation can deliver. Temperature-controlled packaging validation has gained prominence as medical devices with stricter thermal requirements move through broader distribution networks. Testing providers are responding with more refined distribution simulation capabilities, including updates to visual inspection protocols for whole-package evaluation. These improvements allow manufacturers to identify failure modes earlier, reduce field risks, and strengthen confidence in sterile barrier systems before commercialization. The broader trend is a move from minimum compliance testing toward predictive, data-rich validation that supports design decisions and supply chain resilience.
In parallel, the integration of engineering and validation services is becoming a competitive differentiator. Providers that can combine package design, materials evaluation, and performance testing under one roof reduce handoff delays and improve traceability across the validation lifecycle. This convergence is especially valuable for companies introducing novel materials or complex configurations, where traditional siloed testing approaches can slow iteration and increase rework.
Regulatory and Standards Environment
Regulatory clarity is both a stabilizer and a source of new complexity. ISO 11607-1 and -2 continue to anchor validation expectations for terminally sterilized packaging systems, covering design, process validation, and stability testing. However, the broader compliance environment is expanding beyond traditional sterilization and integrity requirements. State-level EPR frameworks are introducing eco-modulated fee structures tied to recyclability, even as many medical device packaging materials remain exempt. For manufacturers and validation partners, this creates a need to monitor jurisdictional nuances, anticipate possible future tightening, and document packaging choices with greater precision. The practical effect is that validation programs must now account not only for performance but also for the evolving sustainability and materials-related expectations that regulators and customers increasingly reference.
Demand-Side Shifts and Device Complexity
Demand for validation is being reinforced by changes on the device side. More devices are being designed for broader distribution footprints, longer shelf life expectations, and more rigorous sterility assurance, all of which raise the bar for packaging performance. At the same time, device manufacturers are under pressure to accelerate development cycles without compromising regulatory submission quality. This creates a dual incentive: reduce time spent on validation rework while ensuring that test programs are robust enough to support submissions and post-market confidence. The result is growing interest in pre-validated packaging approaches, accelerated aging strategies, and integrated testing packages that address multiple requirements simultaneously.
PW Consulting Health Care Research Center
Supply Chain and Cost Structure Dynamics
Cost pressure is reshaping how validation is planned and executed. The recent increase in medical-grade resin prices has affected packaging production economics, which in turn influences validation scope, material selection, and revalidation timing. When material costs rise, the financial penalty of late-stage redesigns or failed validation cycles becomes more significant. This dynamic is pushing organizations to engage validation partners earlier, validate material and process choices more decisively, and consider total cost of ownership rather than testing cost alone. Supply chain disruptions have also underscored the value of distribution simulation and integrity testing that reflect real-world logistics conditions, rather than idealized laboratory settings.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of specialized U.S.-based testing providers, global assurance companies, and integrated service organizations that combine validation with manufacturing or outsourcing capabilities. Market concentration remains moderate, with the top three players accounting for roughly 35 percent of revenue and the top five approaching 49 percent. This level of concentration suggests a market that is still fragmented enough for differentiation, but increasingly attractive for consolidation among players seeking scale, geographic coverage, and expanded service lines.
Several firms illustrate the strategic paths being taken. Westpak has built its position around ISO 11607-compliant validation services, including performance testing, accelerated aging, sterile integrity, and distribution simulation, supported by ISTA-certified testing. Its recent focus on temperature-controlled packaging validation and updated whole-package visual inspection protocols reflects a broader industry shift toward more realistic distribution testing. DDL brings over 35 years of experience as an ISO/IEC 17025 accredited laboratory offering stability, distribution simulation, integrity, and materials testing, positioning longevity and accreditation as trust signals for device manufacturers seeking consistent compliance support. Nelson Laboratories provides end-to-end packaging solutions validation, spanning accelerated and real-time aging, container closure integrity, microbial barrier, strength, and transportation testing, which appeals to customers that want a single partner for multiple validation dimensions.
Packaging Compliance Labs has pursued a more aggressive expansion strategy through acquisition, including the purchase of Quest Engineering Solutions to strengthen East Coast presence and broaden ISO 17025-accredited testing capacity. The opening of PCL East in Billerica, MA, following that acquisition, illustrates how regional coverage and capability expansion are being used to capture demand closer to customers and reduce service friction. Pro-Tech Design & Manufacturing differentiates through a combined model that integrates ISO 13485 and ISO 17025 certified contract manufacturing with packaging validation, assembly, and pre-validated packaging, offering a turnkey route for clients that want to reduce coordination overhead. Life Science Outsourcing adds further variety by pairing package testing and validation with assembly and sterilization services, supported by ISTA-certified lab capabilities, which can be attractive for companies seeking to consolidate multiple operational steps.
On the global side, SGS and TÜV SÜD leverage broad regulatory and testing footprints to serve multinational device manufacturers that need harmonized support across regions and standards. NAMSA rounds out the landscape by embedding packaging validation, seal integrity, simulated distribution, and shelf-life determination within a wider medical device testing portfolio, positioning validation as part of a comprehensive product development and compliance pathway.
The strategic implications are becoming clearer. Leading providers are pursuing one or more of the following advantages: geographic expansion to shorten response times and serve regional demand; capability integration that links validation with design, manufacturing, or sterilization; and service breadth that reduces the number of external handoffs for device companies. At the same time, the market is likely to see continued differentiation between specialists that offer deep, narrowly focused validation expertise and broader service platforms that compete on convenience, scale, and end-to-end continuity. New entrants may find opportunities in regional niches, temperature-sensitive packaging validation, or specialized materials testing, but gaining trust will depend on accreditation, demonstrated compliance support, and the ability to handle increasingly complex device and distribution scenarios.
Future Trends and Commercial Implications
Looking ahead to the next three to five years, several trends are likely to shape the market. First, validation is expected to become more integrated with early-stage package design and supply chain planning. As device manufacturers face higher material costs and more demanding distribution requirements, the cost of late-stage validation failures will continue to rise. This should drive greater adoption of pre-validated packaging concepts, earlier distribution simulation, and more coordinated engineering-test workflows. The commercial opportunity lies with providers that can help customers reduce iteration cycles while maintaining regulatory confidence.
Second, the regulatory and sustainability conversation will keep expanding, even where direct medical device packaging exemptions remain in place. State EPR frameworks and eco-modulation concepts are creating a backdrop in which packaging choices are scrutinized not only for performance but also for materials handling, recyclability, and long-term compliance risk. Validation programs will need to document material selection and performance in ways that support both regulatory submissions and internal sustainability governance. Providers that can bridge performance testing with materials and compliance advisory services will be better placed to capture this growing need.
Sterile Medical Packaging Market
Third, demand for temperature-controlled and distribution-realistic testing is likely to keep rising as devices travel through more complex logistics networks and as visual inspection and integrity testing methods become more refined. This trend creates openings for labs that can deliver clinically relevant simulation, consistent accreditation, and clear reporting that supports both internal decision-making and external submissions. The associated risk is that test expectations may continue to evolve faster than some providers can scale capacity or update protocols, which could create uneven service quality across the market. Organizations should also monitor the possibility of further regulatory or standards updates that could shift validation requirements, particularly in areas related to sterility assurance, stability, and materials documentation.
Plastic Medical Packaging Market
Actionable Recommendations for Decision-Makers
For medical device manufacturers, the priority is to treat package validation as a strategic input rather than a late-stage gate. Engaging validation partners earlier, aligning test plans with distribution realities, and considering materials cost and supply risk during design can reduce rework and shorten time to market. Companies should also document packaging decisions with enough clarity to address both performance requirements and the evolving sustainability and materials context that regulators and customers are increasingly watching.
For investors, the market offers appeal through steady growth, moderate concentration, and ongoing consolidation activity. The most resilient opportunities are likely to be found in providers with strong accreditation, regional expansion momentum, and the ability to integrate validation with adjacent services such as design, assembly, sterilization, or distribution simulation. Due diligence should focus on capacity scalability, protocol update capability, and exposure to raw material and regulatory variability.
For procurement and quality leaders, selecting validation partners should involve more than comparing test cost. Accreditation status, service breadth, geographic coverage, and the ability to support temperature-controlled and distribution simulation testing are all relevant to long-term risk management. Building relationships with providers that can scale with product complexity and supply chain changes will help reduce friction as portfolios grow and distribution requirements become more demanding.
For organizations seeking a deeper, segment-level view of growth rates, regional dynamics, test-type mixes, packaging format trends, and company-level benchmarking, a more granular research perspective can support tailored planning and investment decisions. Detailed datasets and customized scenario analysis can help translate these market-level insights into specific operational priorities, whether the goal is capacity planning, partner selection, or competitive positioning.
For detailed analysis of this topic, please visit the official page: Medical Device Package Validation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
LAN Access Point Market: Why Wi-Fi 7, 9.18% CAGR, and Enterprise Demand Are Redefining Growth
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide LAN Access Point Market
Market Landscape: Navigating Growth Amidst Structural Shifts
The Worldwide LAN Access Point Market is experiencing a period of robust expansion, characterized by a significant upward trajectory in revenue over the past half-decade. Valued at approximately $8.15 billion in 2020, the market has climbed to a projected $12.45 billion in 2025. This growth is not merely a recovery from pandemic-era disruptions but reflects a fundamental shift in how organizations deploy and manage wireless infrastructure. Looking forward, the market is anticipated to sustain a compound annual growth rate of 9.18% through 2032, potentially reaching $23.02 billion. This expansion underscores the critical role that reliable, high-speed local area networking plays in the broader digital economy, serving as the backbone for enterprise operations, educational institutions, and public sector services.
Despite the optimistic revenue figures, the industry stands at a critical juncture defined by several key challenges. First, the transition to next-generation standards is creating a bifurcation in the market. While newer protocols are gaining traction, a substantial portion of the installed base remains reliant on legacy technologies, creating a complex environment for vendors managing support, compatibility, and upgrade paths. Organizations must balance the immediate need for connectivity with the long-term necessity of future-proofing their infrastructure, often amidst constrained budgets.
Second, infrastructure readiness presents a notable hurdle. The performance benefits of advanced access points are inherently tied to the quality of the wired backhaul supporting them. In many regions, the existing copper or fiber infrastructure requires significant upgrades to handle the throughput and low latency promised by newer wireless standards. This dependency adds a layer of complexity and cost to deployment projects, potentially slowing adoption rates in areas where civil works or cabling upgrades are prohibitively expensive or logistically challenging.
Worldwide WLAN Access Points Market
Finally, market concentration remains high, with the top three players controlling a significant majority of the revenue share. This consolidation creates barriers to entry for smaller innovators and can lead to pricing pressure or reduced differentiation in mature segments. However, it also suggests that the market is moving towards standardized, mature solutions where network effects and ecosystem integration become more valuable than standalone hardware specifications. Decision-makers must navigate this concentrated landscape by evaluating not just hardware capabilities, but the broader manageability and security ecosystems offered by dominant providers.
Key Drivers Fueling Market Expansion
Technological Innovation and the Wi-Fi 7 Transition
The primary engine driving market growth is the rapid technological evolution from Wi-Fi 6 and 6E towards Wi-Fi 7. This shift represents more than a incremental speed increase; it is a fundamental change in network architecture designed to support higher density and lower latency. Wi-Fi 7 introduces features such as multi-link operation and wider channel bandwidths, which are critical for modern enterprise applications requiring consistent performance across diverse devices. Early commercial deployments in 2025 indicated a swift uptake, with next-generation protocols capturing a significant portion of revenue in the dependent access point segment by the end of the year. Vendors have responded by accelerating product roadmaps, releasing tri-band access points that maximize throughput for high-density environments. This technological leap is compelling organizations to reconsider their refresh cycles, moving from periodic maintenance upgrades to proactive infrastructure modernization to support AI-driven workloads and high-bandwidth applications.
Regulatory Mandates and Public Infrastructure Investment
Policy and regulatory environments are increasingly shaping demand dynamics. In early 2025, legislative moves such as the European Union's 'Connected Continent' regulation mandated Wi-Fi coverage in public buildings and transport hubs. Such policies directly stimulate procurement in the government and public sector verticals, transforming wireless LAN access from a discretionary IT expense into a compliance requirement. Beyond regulation, broader infrastructure investment trends are creating a supportive backdrop. Global spending on data center infrastructure is projected to grow substantially over the next five years, with significant implications for the connectivity required to support wireless access points. As organizations invest heavily in AI-ready facilities, the demand for robust LAN access points that can seamlessly integrate with high-performance backend networks increases. This correlation between broader digital infrastructure spending and LAN access point deployment suggests that public and private investment cycles will remain a strong tailwind for the market.
Shifting Demand Patterns in Enterprise and SMB Segments
Demand-side behavior is evolving as organizations recognize wireless not just as a convenience, but as a primary access medium. Enterprises are prioritizing high-density deployments to support hybrid work models, IoT integration, and real-time data analytics. The expectation for seamless connectivity has raised the baseline for Service Level Agreements (SLAs), pushing IT leaders towards solutions that offer AI-driven management and automated troubleshooting. Simultaneously, the Small and Medium Business (SMB) and prosumer segments are seeing increased sophistication in requirements. Affordable, scalable solutions utilizing mesh architectures and Wi-Fi 7 capabilities are becoming standard even in smaller environments, driven by the proliferation of high-bandwidth consumer devices and smart home ecosystems. This democratization of high-performance wireless technology expands the total addressable market, allowing vendors to capture growth in segments previously dominated by legacy or lower-tier products.
Supply Chain Dynamics and Infrastructure Costs
The cost structure of deploying LAN access points is influenced by broader supply chain and infrastructure economics. While hardware costs have stabilized, the total cost of ownership is increasingly tied to the underlying network infrastructure. For instance, the cost of building data centers capable of supporting high-density wireless networks has risen, with AI-ready facilities commanding significantly higher investment per megawatt compared to standard builds. These infrastructure cost pressures ripple through to deployment budgets, requiring stakeholders to justify LAN access point investments through clear ROI metrics related to productivity and operational efficiency. Furthermore, the expansion of fiber optic networks, with over 60% of homes in key markets passed by fiber, provides the essential wired backhaul necessary for optimal access point performance. This synergy between fiber expansion and wireless deployment reduces bottlenecks and enables the full realization of new Wi-Fi standards, reinforcing the supply-side readiness for market growth.
Worldwide Wireless Acess Point Controller Market
Competitive Landscape and Strategic Positioning
The market is defined by a mix of entrenched infrastructure giants and agile challengers, each pursuing distinct strategies to capture share. Cisco Systems currently maintains a leadership position in revenue share, particularly in the early adoption of Wi-Fi 7 indoor access points. Their strategy relies on aggressive pricing relative to previous generations and leveraging their massive installed base to drive faster adoption rates during refresh cycles. By integrating access points deeply with their broader networking and security portfolio, Cisco creates a sticky ecosystem that appeals to large enterprises seeking unified management and support.
Hewlett Packard Enterprise (Aruba) represents another pillar of strength, particularly following its acquisition of Juniper Networks. This integration brought Juniper's Mist AI-driven wireless portfolio into the Aruba fold, significantly enhancing capabilities in automated, high-performance LAN access. The focus here is on user experience and operational efficiency, using AI to predict and resolve issues before they impact users. This differentiation is crucial in verticals like education and hospitality, where downtime directly correlates to revenue or learning outcomes. CommScope, through Ruckus Networks, continues to differentiate through reliability in challenging and dense environments, catering to enterprises that require robust performance in difficult physical layouts.
A distinct trend in the competitive landscape is the rise of security-converged networking. Fortinet, for example, integrates its access points into a broader Security Fabric, offering converged networking and advanced security capabilities. This approach addresses the growing concern over network perimeter security, appealing to organizations that prefer a unified threat management approach over siloed security and networking tools. Meanwhile, cost-effective challengers like Ubiquiti, TP-Link, and Netgear are capturing significant volume in the SMB and prosumer spaces. TP-Link's launch of whole-home mesh systems supporting Wi-Fi 7 illustrates how these players are bringing enterprise-grade features to smaller deployments at accessible price points, putting pressure on incumbents to justify premium pricing in lower-tier segments.
The market is evolving through both consolidation and fragmentation. The merger of major players like HPE and Juniper indicates a trend towards consolidation to achieve scale and integrate AI capabilities. However, fragmentation persists in the lower end of the market and in specialized use cases, such as fixed wireless or specific outdoor deployments where niche players like Cambium Networks operate. New entrants or existing players are increasingly competing on software value—management interfaces, analytics, and security—rather than just radio frequency performance. The battleground is shifting from "who has the fastest radio" to "who provides the most reliable and secure operational environment."
Future Outlook: Trends Shaping 2026-2030
Looking ahead, the convergence of AI and network management will likely become the default standard rather than a differentiator. As networks become more complex with the introduction of Wi-Fi 7 and the proliferation of connected devices, manual management will become untenable. Access points will increasingly function as sensors, providing data that feeds into AI models to optimize traffic flow, predict failures, and enhance security posture autonomously. Organizations that adopt infrastructure capable of supporting this AI-driven management layer will see operational efficiencies, while those sticking to legacy manual paradigms may face higher operational costs and reliability gaps.
Another critical trend is the deepening integration of LAN access points with broader cloud and edge computing architectures. As edge computing grows, the access point becomes a key gateway for data moving between endpoints and edge servers. This will drive demand for access points with higher computational capabilities or tighter integration with edge nodes. Furthermore, the regulatory push for public connectivity will likely expand beyond Europe, prompting governments in other regions to consider similar mandates. This could open substantial public sector opportunities, though it also introduces the risk of procurement delays and compliance complexities that vendors must navigate.
However, uncertainties remain. The pace of Wi-Fi 7 adoption could face headwinds if the cost of required infrastructure upgrades—such as cabling and switching—outpaces the perceived immediate benefit for some organizations. Additionally, geopolitical factors affecting supply chains could impact hardware availability and pricing. Security threats will also continue to evolve, requiring access point vendors to stay ahead of vulnerabilities that could exploit wireless vectors. The ability to balance innovation with security and cost-effectiveness will define the winners in the next cycle.
Strategic Actions for Decision Makers
For enterprise leaders and IT planners, the immediate priority should be aligning refresh cycles with the Wi-Fi 7 transition. Delaying upgrades risks falling behind on density and latency capabilities required for modern applications. When evaluating vendors, focus on the software ecosystem and management capabilities rather than hardware specifications alone. AI-driven operations and security integration offer long-term value that outweighs marginal differences in throughput. Procurement teams should also assess the readiness of their wired backhaul infrastructure to avoid bottlenecks that negate the benefits of new access points.
Investors looking at the networking sector should monitor companies that are successfully integrating AI and security into their wireless portfolios. The value creation in this market is shifting towards recurring revenue models based on management software and services, rather than one-off hardware sales. Companies with strong positions in high-growth verticals like education and government, driven by regulatory demand, also present attractive opportunities. Conversely, reliance on legacy hardware without a clear path to next-generation standards poses a risk.
For manufacturers and vendors, differentiation through reliability in challenging environments and specialized vertical solutions remains a viable path against the giants. Expanding into adjacent markets where fiber backhaul is expanding rapidly can also unlock growth. Collaboration with infrastructure providers to ensure seamless integration between wireless access points and fiber networks will be key to reducing deployment friction.
Navigating the LAN access point market requires a nuanced understanding of technology roadmaps, regulatory shifts, and competitive dynamics. While the headline growth figures are encouraging, the real opportunities lie in the details of segmentation, adoption curves, and vendor-specific strategies. Stakeholders seeking to capitalize on these trends should consider accessing granular data to refine their investment theses or procurement strategies. Comprehensive research reports provide the detailed breakdown of regional performance, specific vendor market shares, and deep-dive analysis into sub-segments necessary for precise planning. Engaging with such detailed intelligence ensures that strategic decisions are grounded in the latest market realities rather than generalized assumptions.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide LAN Access Point Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com